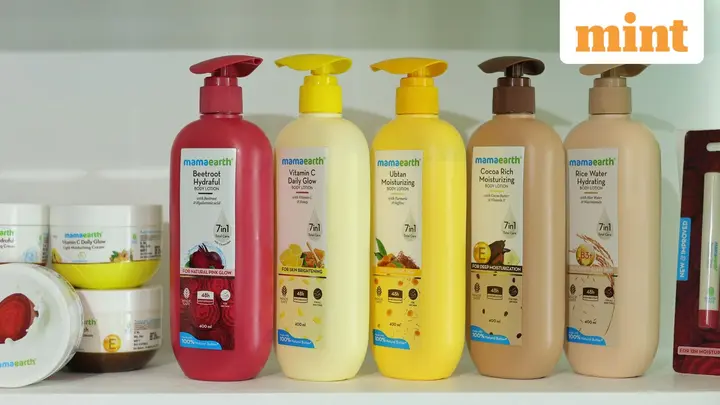
Mamaearth parent Honasa Consumer’s Q2 may raise FY27 earnings expectations
AI Summary
Honasa Consumer's strong sales growth and expanding distribution network indicate a positive trajectory for the company, but retail investors should be cautious. The reliance on trade incentives to boost sales could erode operating margins, and the upcoming Q2 results will be critical in determining if the current stock valuation is justified. Investors should keep an eye on consumer demand trends and the effectiveness of marketing strategies as the company scales its operations.
This is a Mint Premium article gifted to you.Subscribe to enjoy similar stories.
Honasa Consumer’s September quarter (Q2FY27) update thrilled investors, lifting the stock 7% over the past two trading sessions. The company expects year-on-year net sales value (NSV) growth in the early 30s, with its largest brand, Mamaearth, growing in the high teens and younger brands at around mid-40s. It also expects an early double-digit operating margin. This is similar to Q1 when Mamaearth saw high-teens growth and younger brands were up over 40%.
Original Article
Published on Livemint
Frequently Asked Questions
What is this article about?
This is a market news update from Livemint, published on 07 October 2026.
Is this news positive or negative for markets?
TopFund's automated sentiment analysis reads this article as neutral in tone, based on the language used in the report. This is a general signal, not investment advice.
Where can I read the full article?
The full article is available at the original source, Livemint — see the "Read Original Article" link on this page.